


New innovations in global payments are creating faster and more transparent ways to send money across borders. These modern cross-border payment systems are designed to remove delays, reduce complexity, and increase visibility at every step. Whether it’s individuals supporting family abroad or businesses expanding internationally, the ability to move funds quickly and clearly is becoming a new standard, replacing outdated systems that often caused confusion and bottlenecks.
Note: Transfer delivery times vary and are not guaranteed; additional regulatory or compliance reviews can delay funds.
Beyond speed and clarity, today’s cross-border payments are becoming more inclusive, opening access to many previously underserved communities, while still observing U.S. sanctions and other local regulations. These advancements don’t just support individuals, they strengthen entire economies by opening up new opportunities for trade, financial access, and economic mobility. As global payments continue to evolve, the world moves one step closer to a truly connected financial future.
Disclaimer: Order Express, Inc. (OEI) is a licensed Money Services Business. All transfers are subject to verification, compliance screening, and local payout-network availability. Processing times may vary by destination country, regulatory requirements, and payout method.

Why Cross-Border Payments Are Key to Financial Connectivity
In today’s global economy, cross-border payments have become a driving force behind economic inclusion and international growth. Whether it’s a business expanding to new markets or a family sending money across continents, seamless financial transactions are vital for maintaining the rhythm of global trade and personal finance. These payments move billions in value across borders each day, powering everything from supply chains to digital marketplaces. Yet despite their importance, the systems behind them are undergoing long-overdue transformation.
For decades, traditional banking networks have handled international payments with limited speed, transparency, and accessibility. But that’s changing fast. Driven by the rise of digital solutions and increasing demand for real-time transfers, cross-border payments are evolving to better serve a connected world. From back-end innovations to improved user experiences, every link in the payment chain is being reimagined. As we explore what’s changing, why it matters, and what challenges remain, one thing is clear: global payment systems are no longer just infrastructure, they’re enablers of global progress.
Understanding Cross-Border Payments in the Global Economy
Cross-border payments refer to financial transactions where the sender and recipient are based in different countries. These transactions are essential to international trade, global business, and personal remittances. Whether it’s a business settling invoices or an individual sending funds to family abroad, cross-border payments occur through several channels, including bank transfers, credit card transactions, mobile payments, and digital wallets. These methods are used across both wholesale and retail sectors, enabling the smooth flow of payments across borders in a fast-paced, interconnected world.
Behind the scenes, these payments are routed through networks that help different financial systems communicate, even when they operate independently. Traditionally, this process relied on Correspondent Banking Networks, where banks maintained reciprocal accounts to manage transfers. Today, newer infrastructures are enhancing the speed, security, and efficiency of cross-border payments by creating connections between domestic systems. These advancements allow businesses and individuals to send and receive payments more easily, supporting the continued evolution of global payments without the need to physically move funds across borders.
Why Cross-Border Payments Are Ready for Global Change
Globalization has transformed how people and businesses operate across borders. From international trade and freelance work to digital services and global supply chains, the demand for reliable cross-border payments has soared. Yet, despite this growing need, many payment systems still operate on outdated infrastructure, creating frustrating delays and access barriers. These inefficiencies not only slow down financial growth, they also limit opportunities for broader inclusion.
Fortunately, this is beginning to change. A new wave of innovation is addressing the weaknesses of traditional payment systems and offering better alternatives. Here’s what’s driving this transformation:
- Faster settlement options are reducing the long wait times associated with older networks.
- Digital-first infrastructures are helping reach regions that were previously underserved.
- Smarter routing systems are streamlining transactions and enhancing transparency.
- Improved user interfaces are making international transfers easier for individuals and small businesses.
- Focus on financial inclusion is ensuring solutions are designed for accessibility and affordability.
As these changes take hold, the future of cross-border payments looks brighter than ever. New models are empowering individuals and businesses to participate in the global economy without friction. These advances are especially impactful in developing regions, where access to fast, transparent payments can create lasting economic improvements. With more responsive systems and inclusive designs, the global payment ecosystem is evolving into a stronger, smarter, and more connected financial network. The momentum is real, and the change is already underway.
What Challenges Still Affect Cross-Border Payments?
Cross-border payments continue to face several barriers that slow their progress compared to domestic transactions. While sending money within a single country has become faster and more efficient, international payments can still be delayed by inconsistent data formats, limited processing hours, and outdated infrastructure. Many systems rely on legacy technology that wasn’t built for today’s fast-paced digital economy. As a result, processing speeds are slower, automation is limited, and tracking payments in real time becomes difficult. In addition, long value chains and the need to meet various global compliance checks can introduce unnecessary delays and make the process feel opaque to users.
Despite these challenges, the push toward improving cross-border payments is gaining momentum. Modernizing infrastructure, streamlining data formats, and expanding settlement operating hours are essential next steps. With smoother systems, institutions can reduce delays, improve transparency, and increase access for people and businesses that rely on global payments. The complexity of navigating multiple jurisdictions and time zones is real, but coordinated international efforts are paving the way for a faster, safer, and more reliable cross-border payment experience.
How Cross-Border Payments Are Powering Global Progress
Cross-border payments are undergoing a major transformation as global commerce becomes more digital and interconnected. Traditional payment systems, once marked by inefficiencies and limited transparency, are now being replaced with smarter, more agile technologies. This shift is enabling a smoother, faster, and more user-focused experience for businesses and individuals sending or receiving money internationally.
Here’s how innovation is reshaping the future of global payments:
- Near real-time processing lets many, but not all, corridors deliver funds in minutes; delivery depends on destination rules and compliance screening.
- End-to-end visibility gives users real-time updates on payment status.
- Advanced security measures reduce fraud risks and protect sensitive data.
- Interoperable systems enable different financial platforms to communicate more effectively.
- Inclusive infrastructure expands access to financial services across underserved regions.
These improvements are more than just technical upgrades, they create real impact. Individuals can now send money abroad with greater ease, while businesses can settle international transactions without delays. Financial institutions benefit from more streamlined operations, reducing manual work and improving accuracy. As cross-border payments become more accessible and reliable, they’re not just supporting the global economy, they’re actively shaping its future. The rise of real-time, digital-first solutions signals a powerful shift toward financial systems that are inclusive, responsive, and built for global progress.

Why Cross-Border Payments Are Powering the Digital Economy
Cross-border payments are undergoing a major transformation, fueled by shifting consumer behaviors, the rise of digital creators, and evolving expectations in global commerce. What was once a rigid, bank-led process is now becoming more fluid, user-friendly, and inclusive. People expect instant, transparent, and secure transactions whether they’re buying a product, tipping a creator, or settling international business invoices. Payment systems are being reimagined to integrate directly into daily digital experiences, making it easier to send and receive money across borders without friction.
This evolution is not only enhancing convenience, it’s also empowering new participants in the global economy. From individual content creators earning income worldwide to small businesses expanding into new markets, seamless cross-border payments are unlocking opportunities at every level. Behind the scenes, improved interoperability, enhanced security protocols, and smarter infrastructure are aligning to support this growth. As global payments become more interconnected, the barriers that once limited international participation are steadily being dismantled. The future of cross-border commerce depends on a system that is fast, flexible, and built to meet the needs of a truly global audience.
How Cross-Border Payments Are Shaped by Consumer Expectations
Modern consumers demand more than just products, they expect convenience, speed, and simplicity at every step of the purchase journey. Nowhere is this more critical than at the checkout stage. A slow or confusing payment experience can instantly drive customers away, especially in international transactions. As a result, businesses are rethinking how they handle cross-border payments to meet these rising expectations. Instead of treating payment as a separate step, smart platforms are now embedding it directly into the shopping flow to reduce friction and increase conversions.
Here’s how today’s payment experiences are adapting to global consumer needs:
- Near-instant payment options that speed up transactions and minimize delays
- Embedded checkout systems that make the process seamless and intuitive
- Multi-device compatibility, ensuring smooth transitions between mobile and desktop
- Localized payment methods that reflect customer preferences in different regions
- Increased automation to simplify approvals, verifications, and confirmations
These innovations aren’t just upgrades, they’re becoming the baseline for what customers expect from a global payment system.
As these shifts take hold, cross-border payments are evolving into experiences that feel almost invisible. Consumers no longer want to think about how or where a payment is processed, they just want it to work, instantly and securely. Businesses that adapt will be better positioned to build trust and boost loyalty in international markets. The future of cross-border commerce belongs to brands that make payments effortless, integrated, and tailored to the expectations of a connected global audience.
Empowering Creators Through Cross-Border Payments
During global lockdowns, creators, from artists to educators and media makers, sparked a digital renaissance. Social platforms became global stages, connecting audiences across continents. As a result, the creator economy flourished, giving rise to millions of individuals who now see content creation as a profession. The digital shift opened new possibilities for micro-payments, allowing fans to support creators directly for small-scale content, services, or experiences. However, the ability to make these payments seamlessly across borders is still evolving.
Cross-border payments play a critical role in unlocking consistent revenue for creators worldwide. While innovative technologies like biometric authentication and alternative payment rails are simplifying user experiences, low-value transactions still face limitations due to technical inefficiencies. The global payments ecosystem is gradually adapting by introducing more frictionless and accessible tools. As this momentum continues, creators can look forward to more inclusive and efficient systems that support micro-transactions on a global scale, fueling a more connected and empowered digital economy.
Enhancing Cross-Border Payments Through Interoperability
As global trade continues to grow, the demand for seamless cross-border payments is increasing, especially among small and medium-sized enterprises. These businesses play a vital role in the international supply chain, yet they often face challenges when navigating global payment systems. One major hurdle lies in the final step of the payment journey, which can be inconsistent due to differing regulations, infrastructure gaps, and political landscapes. This is particularly true in emerging markets, where limited access to traditional banking services creates roadblocks for efficient transactions.
To address these issues, the financial ecosystem is shifting toward improved interoperability between local and international payment systems. By strengthening the connections between networks, new payment infrastructure is being designed to reduce friction and support more inclusive participation in global payments. These innovations are laying the groundwork for faster, more reliable, and more accessible cross-border transactions, ultimately empowering businesses of all sizes to participate more fully in the global economy.
Optimizing Security in Cross-Border Digital Payments
As digital transactions continue to expand across borders, the need for stronger security measures has become a top priority. Cross-border payments are rising in volume and value, connecting people, businesses, and economies faster than ever before. However, with increased connectivity comes greater vulnerability. The global push toward digital payments demands systems that can not only support speed and scale but also ensure trust, safety, and compliance across international boundaries.
To keep pace with evolving risks, the financial industry is adopting advanced technologies that strengthen protection without compromising the payment experience. Here are key innovations helping shape a safer cross-border environment:
- Biometric authentication: Fingerprint and facial recognition ensure that only authorized users can access accounts.
- Secure digital identities: Verified credentials make it easier to confirm identities across jurisdictions.
- Multi-factor authentication: Adding extra steps beyond passwords helps block unauthorized access.
- AI-driven fraud detection: Machine learning models flag unusual patterns in real time.
- Automated compliance tools: These streamline regulatory checks while reducing manual intervention.
The growing use of these tools reflects a global shift toward proactive security in international transactions. Biometric and identity-based safeguards offer personalized protection, while AI helps scale fraud prevention in complex payment flows. By implementing these solutions at every touchpoint, cross-border payment systems are becoming more resilient and user-friendly. This not only reduces exposure to fraud but also builds confidence among users, encouraging broader adoption and unlocking the full potential of global digital commerce.
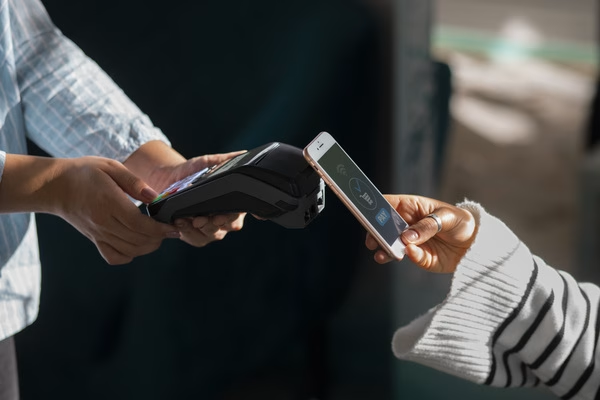
Unlocking the Infrastructure Behind Seamless Cross-Border Payments
As the demand for efficient and inclusive global payments accelerates, the systems powering them are evolving just as rapidly. Beyond the visible interfaces that consumers interact with, there exists a robust digital foundation working behind the scenes to ensure every transaction crosses borders quickly, securely, and reliably. From digital money transfer operators to back-end networks, these players are reshaping how the world moves money, especially in underserved regions and fragmented financial landscapes.
At the heart of this transformation are strategic partnerships and advanced infrastructure models that respond to both local challenges and global expectations. Whether by bridging gaps in emerging markets or enabling instant transfers through aggregation models, these innovations are making cross-border payments faster and more accessible than ever. The integration of local networks with broader digital systems is not only improving operational efficiency but also laying the groundwork for a more inclusive and connected global economy.
How Digital Money Transfer Operators Support Cross-Border Payments
Digital money transfer operators play a central role in global payments by serving as a bridge between senders, whether individuals or businesses, and recipients across borders. These operators are purpose-built for cross-border transactions and often establish direct financial pathways between countries. When handling traditional currencies, they build banking relationships in both the sending and receiving regions to enable circular money flows. However, in emerging markets, gaining access to formal banking channels can be challenging. Regulatory limitations and restricted capital mobility can make cross-border movement more complex.
To navigate these hurdles, digital money transfer operators increasingly partner with local payment networks to complete transactions smoothly. In areas where financial inclusion is limited and local payment systems are fragmented, such partnerships allow for broader reach and better accessibility. This approach enhances the reliability and scalability of cross-border payments while helping support economic participation in underserved regions. By integrating local infrastructure into a broader digital framework, these operators are helping to build a more inclusive and connected global payment system.
How Back-End Networks Are Reshaping Cross-Border Payments
Back-end networks are quietly transforming how money moves across borders. Although they don’t interact directly with senders or recipients, their influence behind the scenes is significant. These systems create direct connections with financial institutions and local payment methods across diverse regions. By bridging gaps in traditional infrastructure, they make cross-border payments more streamlined, accessible, and responsive to today’s global demand. As financial ecosystems evolve, more global providers are turning to these agile back-end networks to replace slower, legacy systems and to improve delivery times.
Here’s why these networks are becoming essential to modern global payments:
- Regional focus: Most networks specialize in specific countries or regions to navigate local rules and regulations more effectively.
- Aggregation models: These allow payment providers to manage multiple connections through a single interface, improving scalability and reducing complexity.
- Faster settlements: Real-time processing is often enabled by pre-funding transfers, leading to quicker delivery times.
- Improved transparency: Clearer transaction tracking and communication provide better visibility for both senders and recipients.
- Support for low-value transfers: Ideal for individual or business-to-customer payments, where speed and cost efficiency matter most.
While these models haven’t fully penetrated the high-value B2B sector, their impact on global payments is undeniable. They’re especially effective in expanding access to regions that were once difficult to reach. By reducing friction and increasing efficiency, back-end networks empower businesses and individuals alike. As innovation continues, their role in cross-border payments will only grow, unlocking new possibilities for financial inclusion and economic expansion.
Consumer Protection & Compliance
OEI screens every transaction against U.S. sanctions lists and anti-money-laundering rules. Personal data is safeguarded in accordance with the Gramm-Leach-Bliley Act privacy standards. For questions, error resolution, or cancellation requests, contact us:
- Customer Service: 1-888-666-1602
- Compliance Dept: +1 312-235-5219
- Email: customer.service@orderexpress.com
- Mail: Order Express, Inc., 685 W. Ohio St., Chicago IL 60654
Conclusion
Cross-border payments are no longer confined to slow systems and limited access. Innovation is redefining how money moves globally, faster, safer, and more inclusively. From enhanced interoperability to smarter back-end networks, every upgrade brings us closer to a truly connected financial future. These changes don’t just benefit institutions; they empower individuals, creators, and businesses to participate in the global economy with confidence. As global payment infrastructure continues to evolve, it’s time for businesses and users to embrace modern solutions and take full advantage of seamless, transparent cross-border payment experiences.
All services are provided in compliance with applicable U.S. federal and state regulations, including the Bank Secrecy Act, USA PATRIOT Act, and Consumer Financial Protection Bureau (Remittance Transfer Rule).
FAQs
What are cross-border payments?
Cross-border payments are financial transactions between people or businesses in different countries.
Why are cross-border payments important?
They support global trade, personal remittances, and economic participation across international markets.
What challenges affect cross-border payments?
Outdated infrastructure, slow processing, and regulatory differences can delay or complicate transfers.
How are cross-border payments becoming faster?
Digital-first systems, real-time settlements, and smarter routing improve speed and transparency.
Who benefits from improved cross-border payments?
Individuals, creators, businesses, and underserved regions gain faster access to global financial services.
John is a Content & SEO Specialist who enjoys breaking down complex financial topics, like cross-border payments and money transfers, into content that’s easy to understand. He focuses on creating practical, search-driven content that helps people find answers and make informed decisions.


